Chapter 2 - The Fallout and the Unraveling
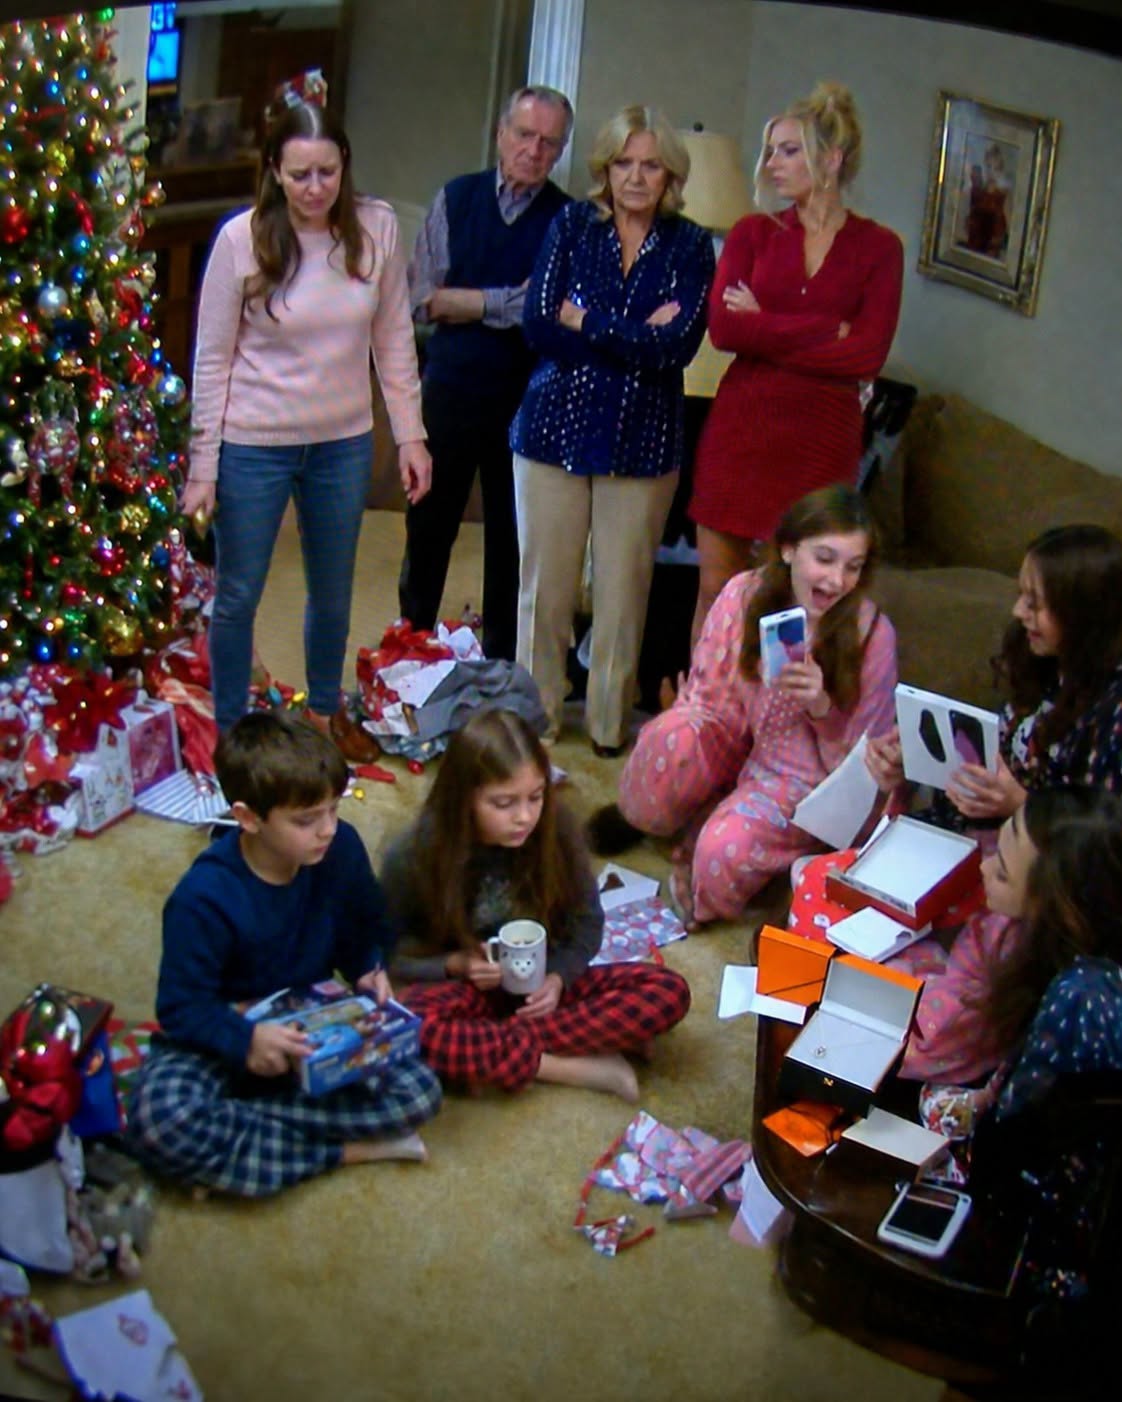
The bottom was actually a moving target, and over the next seventy-two hours, my family proved just how far they were willing to sink to preserve the illusion that they were the victims.
By Christmas afternoon, the shockwaves of my late-night financial surgical strike had fully registered across three households. I had turned off my phone, but my laptop remained open on the kitchen counter, notifications silently pinging like radar pings in a submarine under attack. Without my financial life-support system active, the fragile superstructure of my family's middle-class lifestyle began to collapse with astonishing speed.
The first domino was the Disney cruise. Because I had canceled the remaining balance before the final midnight cutoff window, the reservation system automatically invalidated the deposit, released the ocean-view suite, and sent a automated cancellation notice to Marlene’s email address. The cruise line hit her with a non-refundable forfeiture fee on the minor upgrades she had charged directly to the shared card—a card that was now frozen solid.
When Marlene attempted to call customer service to demand they restore the trip using "her sister's standing account," she was informed that without a valid primary credit card on file, the reservation was permanently dissolved. Her children’s dreams of character breakfasts and waterslides evaporated before noon on Christmas Day.
Next came the luxury items under the tree. Marlene had bought the high-end electronics on the emergency credit card I kept for medical and household crises—a card she had quietly added herself to as an authorized user three years prior during a period when she claimed she needed it "just for gas while job hunting." Over time, that privilege had morphed into a personal line of credit. When I placed a total administrative hold on the account at 1:45 a.m., the bank's automated fraud detection system triggered a retrospective review. Because the billing address on the account was mine, but the recent luxury point-of-sale charges had been made at a suburban Apple Store three miles from Marlene’s house, the system flagged the transactions.
By 2:00 p.m. on December 25th, Marlene received an automated text message from the credit card issuer notifying her that pending authorizations were being revoked and that the primary cardholder—me—had disputed unauthorized recurring usage.
My parents’ house was faring no better. For six years, I had maintained the utility autopay to ensure my aging parents didn't accidentally forget an electric bill during the harsh Maryland winters. However, over the past eighteen months, my father had quietly upgraded their utility tier to include premium digital packages, whole-house high-speed fiber internet, and an elaborate home security monitoring subscription that cost nearly four hundred dollars a month on its own. He had simply assumed the extra line items would blend into the monthly total I paid without question.
When the automated clearinghouse transfers failed at 2:00 a.m. due to the revocation of ACH authorization, the utility companies sent instant notifications to the primary email on file: mine. I systematically unlinked my checking account, updated the service contacts to my father's primary email address, and left the balances standing.
The silence that followed the police officers' departure on December 26th lasted less than three hours. By midday, my mother had initiated a secondary campaign: public shaming through extended family networks and social media.
My phone, once turned back on with a newly created private number for essential contacts, began receiving forwarded screenshots from cousins, aunts, and old family friends. My mother had posted a long, tear-drenched narrative on Facebook, complete with a picture of Caleb’s discarded dollar-store game and Nora’s snowman mug, framing the scene with astonishing revisionist history.
“Heartbroken this holiday season,” her post read. “Our daughter Susan has cut off her elderly parents without warning, leaving us without heat guarantees or mortgage security, all over a simple family misunderstanding about holiday budget limits. She took her children and fled into the night, refusing to let them spend Christmas with their grandparents. We are praying for her mind and her heart. Please do not judge her; she is clearly going through a dark episode.”
The comments under the post were predictable at first. Distant relatives offered prayers, expressing shock that "sweet Susan" could act so cruelly. But my mother had made a critical tactical error: she forgot that digital footprints leave undeniable trails, and she under-estimated how many people in our extended circle had watched her treat me like a personal ATM for over a decade.
My cousin Marcus, a forensic accountant who had lived through his own share of family drama, was the first to comment publicly under her post.
“Aunt Evelyn,” Marcus typed directly beneath her plea for prayers. “Isn't Ronnie paying the mortgage on your home on Elm Street? And didn't she pay off Marlene’s bankruptcy settlement back in 2022? Just trying to understand which part of this is a misunderstanding and which part is unpaid labor.”
The post was deleted within twenty minutes, but not before three different cousins took screenshots and circulated them through a family group chat that had explicitly excluded my parents and Marlene for years.
Meanwhile, in my own living room, the reality of what I had done began to set in. Caleb sat at the kitchen island, drinking hot chocolate from a plain ceramic mug, watching me clean the counters with precise, methodical movements.
“Mom?” he said softly.
I paused, rag in hand, looking at him. His dark eyes—so much like his late father’s—were watching me with a maturity no twelve-year-old boy should have to carry.
“Are we going to be okay financially?” he asked. “I mean... without them?”
The question broke my heart, but it also crystallized my resolve. He thought they were supporting us. He thought that by walking away from that house, we had somehow walked away from our own safety net. My parents had spent years creating an inverted reality where they made me feel like I needed their permission to exist, while quietly draining my resources to maintain their own comfort.
I walked over, sat on the stool beside him, and pulled out my tablet. I opened my primary bank account—the clean one, the one free of secondary cards, shared drafts, and family overdraft protections.
“Caleb,” I said gently, turning the screen toward him. “Look at this.”
He looked at the bottom-line balance. It wasn't just healthy; without the monthly drain of my parents' mortgage, Marlene’s car note, and the endless stream of "emergency" transfers, my monthly surplus was larger than my mortgage payment on our own home.
“I have been paying for two households for five years, sweetie,” I told him, keeping my voice steady and clear. “We aren't going to lose anything. In fact, for the first time in a very long time, we are actually free.”
He looked at the number, then up at me, a slow relief washing across his face. “So... Grandma and Grandpa were using your money?”
“Yes.”
“And they gave us a seven-dollar game with your money?”
“Yes.”
Caleb looked down at his hands, then let out a small, breathless laugh that was half disbelief and half release. “That’s pretty messed up, Mom.”
“It is,” I agreed. “And that’s why we’re never going back.”
That evening, the first legal salvo arrived not from a high-priced attorney, but in the form of a handwritten letter delivered to my doorstep by my father himself, who refused to knock, instead jamming it into the mail slot before hurrying back to his car like a coward.
The letter was written in his signature blocky handwriting, full of underlined words and aggressive punctuation. He demanded an immediate sum of $14,500—which he claimed was the "agreed family contribution" for the remainder of the fiscal quarter—and threatened to file a lawsuit for "breach of verbal contract" regarding the house payments. He also claimed that my adoption of Caleb and Nora was "legally vulnerable" because my late husband’s family might want to intervene if they knew I was "mentally unstable."
It was a desperate, ugly threat designed to hit me where I was most protective. But my father had made a fatal miscalculation: he was threatening a woman who had spent seven years working as a senior paralegal for one of the top estate and asset-protection law firms in the state of Maryland.
I didn't cry. I didn't shake. I took the letter, scanned it into a secure digital drive, attached it to a new file folder titled Wilds vs. Wilds Construction & Estate, and picked up my phone to call Arthur Vance—my employer, mentor, and the most terrifying civil litigator in the Baltimore metropolitan area.
May you like
When Arthur answered on the third ring, his voice was rich and calm. “Ronnie? It’s Boxing Day. Unless the courthouse is on fire, why are you calling me?”
“Arthur,” I said, looking out the window at the snow beginning to fall over my small, quiet lawn. “I need to retain the firm. And I need you to unleash everything we have.”