Chapter 4 - The Escalation
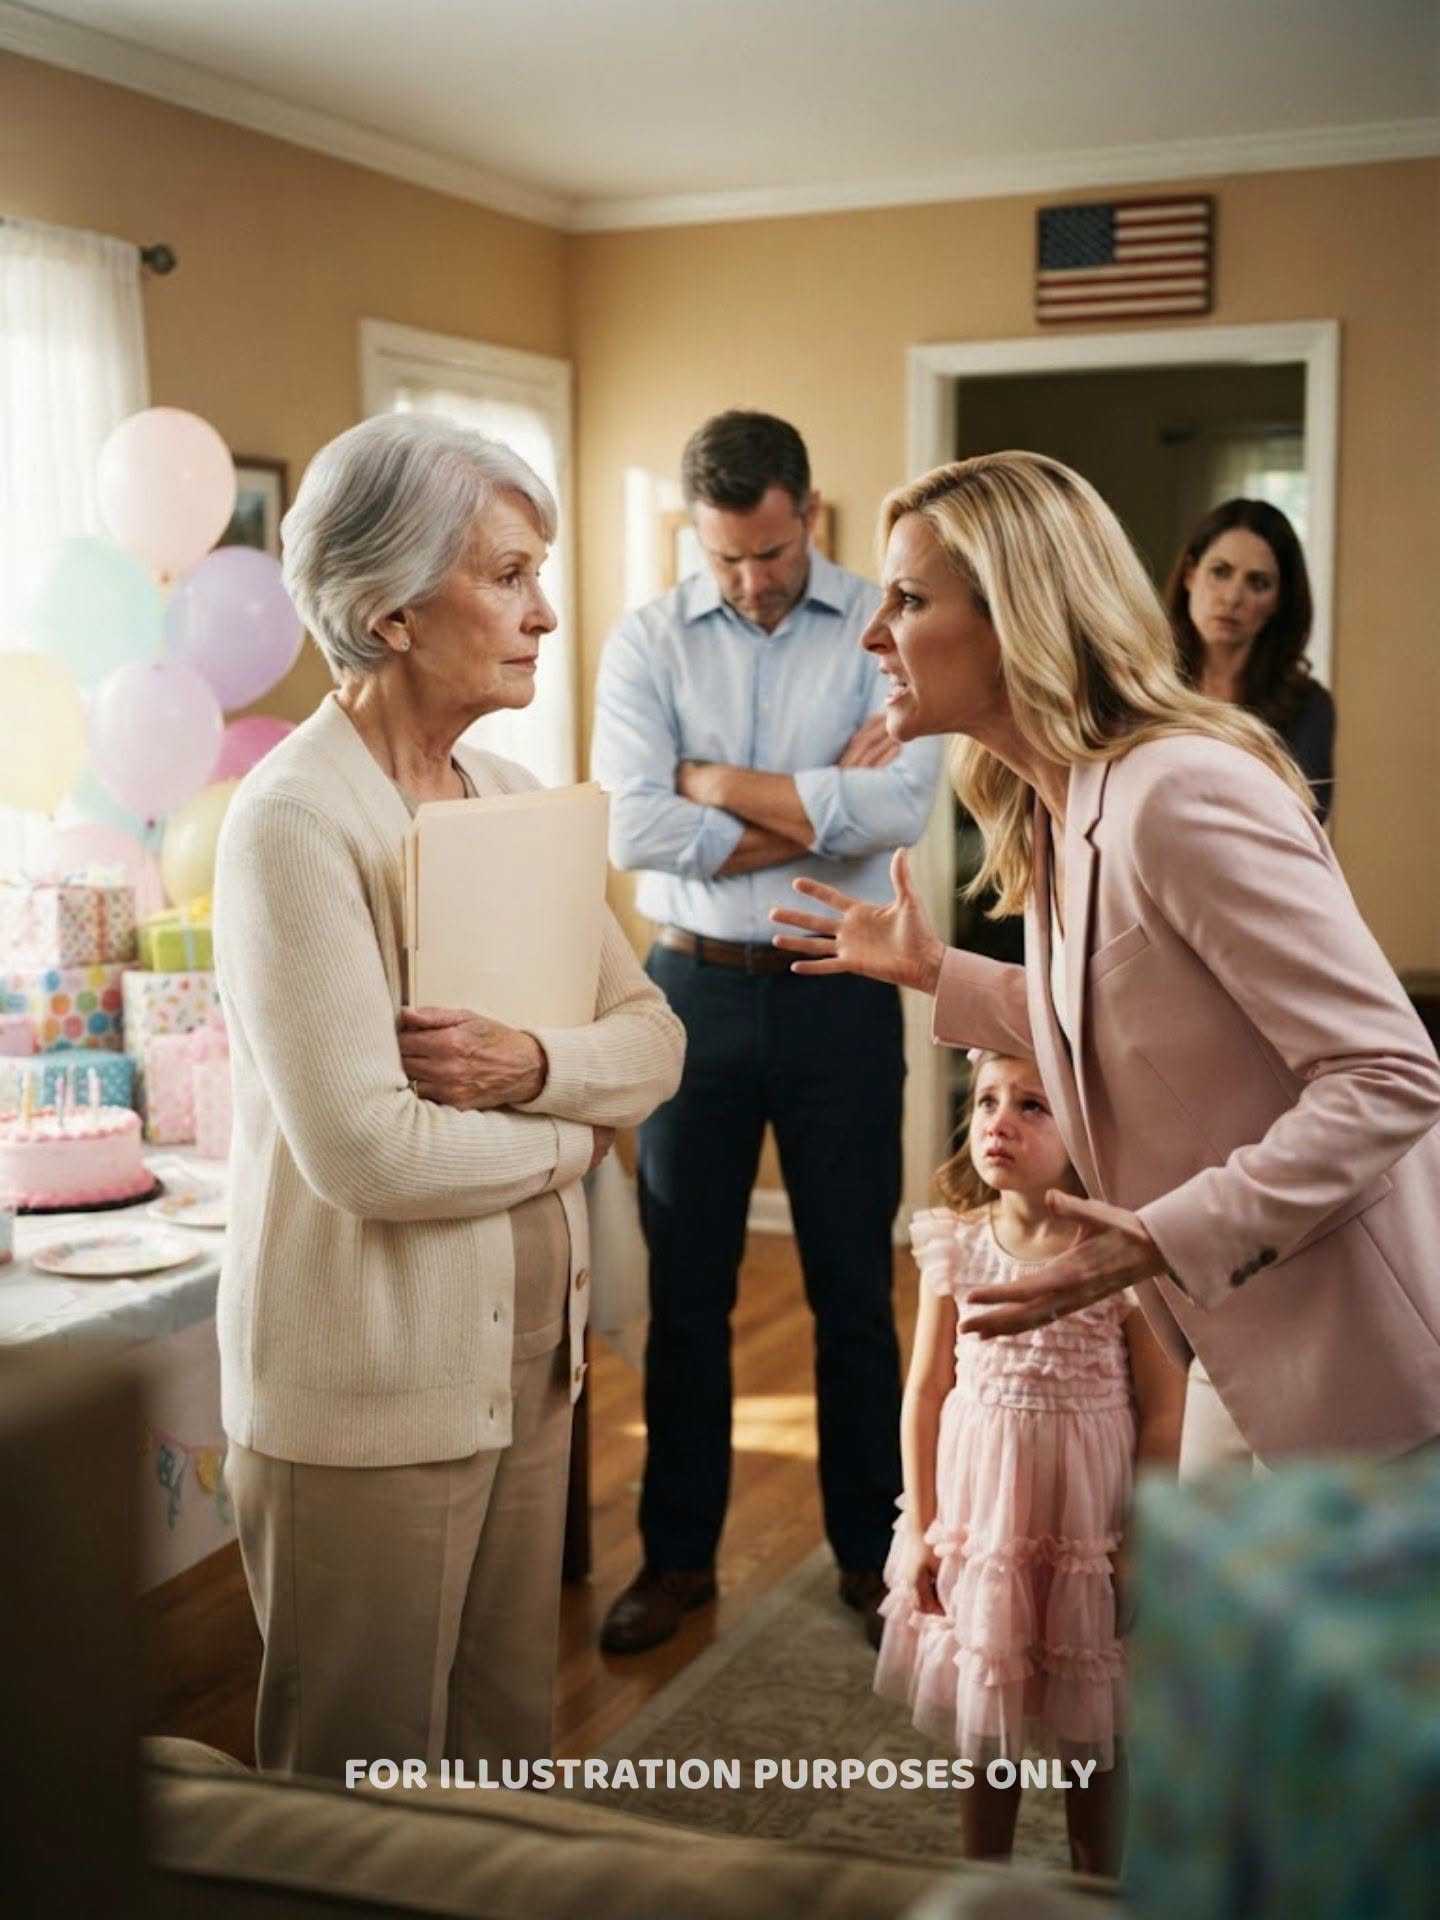
Warfare, when conducted through legal avenues, is rarely loud. It does not consist of screaming matches or tearful reunions; it consists of registered mail, certified notices, and cold, uncompromising deadlines.
By the following Monday, Amber had shifted tactics. Realizing that screeching on my porch had produced zero financial concession, she decided to deploy the weapon she believed held the ultimate emotional value: public shame and legal retaliation.
I received a formal letter from a local family law attorney—a strip-mall practitioner whose letterhead practically bled desperation. The letter alleged 'elderly financial manipulation,' claiming that I had orally agreed to fund Derek and Amber’s household indefinitely as part of an informal family arrangement, and threatened a civil lawsuit for emotional distress and financial hardship unless a settlement was reached.
I took the letter to Thomas Brennan’s high-rise office downtown. Thomas read the document, chuckled quietly, and tossed it into his wastebasket.
“This is amateur hour, Sylvia,” Thomas said, leaning back in his leather chair. “They are bluffing. No court in this state will enforce an alleged 'oral contract' for continuous life subsidies, especially when we have six years of tax filings showing every dollar transferred was logged as an unconditioned gift or a revocable line of credit. Furthermore, their attorney failed to realize that by threatening litigation, they have opened themselves up to a full accounting audit under discovery.”
“I want to move forward with the partition sale of the house,” I said calmly, looking out the window over the city skyline. “And I want a formal custody petition filed for grandparent visitation rights under the state's family code.”
Thomas raised an eyebrow. “Grandparent visitation is a high bar in this jurisdiction, Sylvia. Courts are reluctant to interfere with fit parents.”
“They are not fit,” I replied coldly. “And I am not seeking to take the children away from Derek. I am seeking to ensure that their lives are not dismantled when Amber’s financial fantasy completely collapses. I have paid for Lucas and Sophie’s insurance, their schooling, their pediatric healthcare, and their extracurricular activities since the day they were born. I have an established history of financial and emotional caregiving. Amber is currently using them as human shields to demand trust disbursements. A family court judge will find that very interesting.”
Meanwhile, the economic reality hit Derek’s household like a freight train. Without my $3,500 monthly mortgage supplement, their $5,200 monthly home loan payment devoured nearly 80% of Derek’s take-home pay. Then came the credit cards. Amber had accumulated over $60,000 across four high-interest store and luxury credit cards—balances she had routinely rolled over onto my secondary accounts whenever they reached critical mass.
Without my intervention, the interest rates ballooned. Collections agencies began calling Derek’s office. Her boutique event planning business, devoid of cash reserves, defaulted on two major venue deposits for upcoming autumn weddings. Angry clients began leaving brutal reviews online, demanding refunds that Amber simply did not have.
Rachel kept me informed. She visited Derek’s house on a Wednesday afternoon under the guise of dropping off hand-me-down clothes for Sophie.
“It’s a disaster, Mom,” Rachel told me over dinner that night. “The house is full of unpacked boxes because Amber is panicking about moving, but she refuses to pack properly. She and Derek were screaming at each other in the kitchen while the kids were in the living room trying to watch TV. Derek looks like he hasn't slept in a week. He asked me if I could lend him five thousand dollars just to cover the electricity bill and groceries.”
“Did you?” I asked, looking up from my plate.
“No,” Rachel said firmly. “I remembered what you told me. If I lend him money, I’m just enabling Amber’s denial. I told him he needs to look at his reality. I told him to hire his own lawyer and get his name off Amber’s business debt.”
“Good,” I said. “Derek needs to break his fever. As long as he believes Amber’s lifestyle is his responsibility to fund at any cost, he will remain her prisoner.”
Two days later, Amber made her biggest tactical blunder yet. Desperate for capital to save her failing event business and avoid a public suit from a wealthy bride, she took a forged document to a local private lending firm—a hard-money lender operating on the fringes of commercial finance. She attempted to use the equity in their home as collateral for a $100,000 high-interest loan, signing Derek’s name as well as attempting to forge my signature as the secondary property title holder.
She didn't realize that high-risk lenders perform rigorous title searches before disbursing capital. The lender’s legal department immediately flagged the co-ownership lien held by my trust and called Thomas Brennan’s office to verify the authenticity of my signature.
May you like
Thomas didn't just reject the verification. He called the local District Attorney’s financial crimes division.
The trap had sprung. Amber wasn't just broke anymore. She was facing criminal fraud.